Omnichannel Payment Solutions: A UK Architecture Guide
A customer browses your website on Monday, walks into your store on Thursday and reorders through your app on Saturday. To her, it is one brand. To your payment stack, it looks like three strangers. Each channel runs its own authorisation logic, generates its own settlement file and produces its own reporting view. Reconciling those three views at month-end costs finance teams hours they do not have. An omnichannel payment solution changes that. Instead of connecting channels to separate systems, a unified architecture routes every transaction - online, in-store, in-app - through one platform. One integration, one token vault, one reporting view. This guide explains what omnichannel payment architecture actually means, why UK enterprises are moving towards it, and what to look for when assessing your options.
What Omnichannel Payment Architecture Means
Multichannel and omnichannel are often used interchangeably. They are not the same thing.
A multichannel approach connects each sales channel to its own payment stack. Online uses one gateway, in-store uses a different terminal estate, and the mobile app connects to a third processor. Each channel authorises, settles and reports independently. When a customer uses two channels in the same purchase journey - buying online and returning in-store, for example - the two transactions appear in two separate systems with no connection between them.
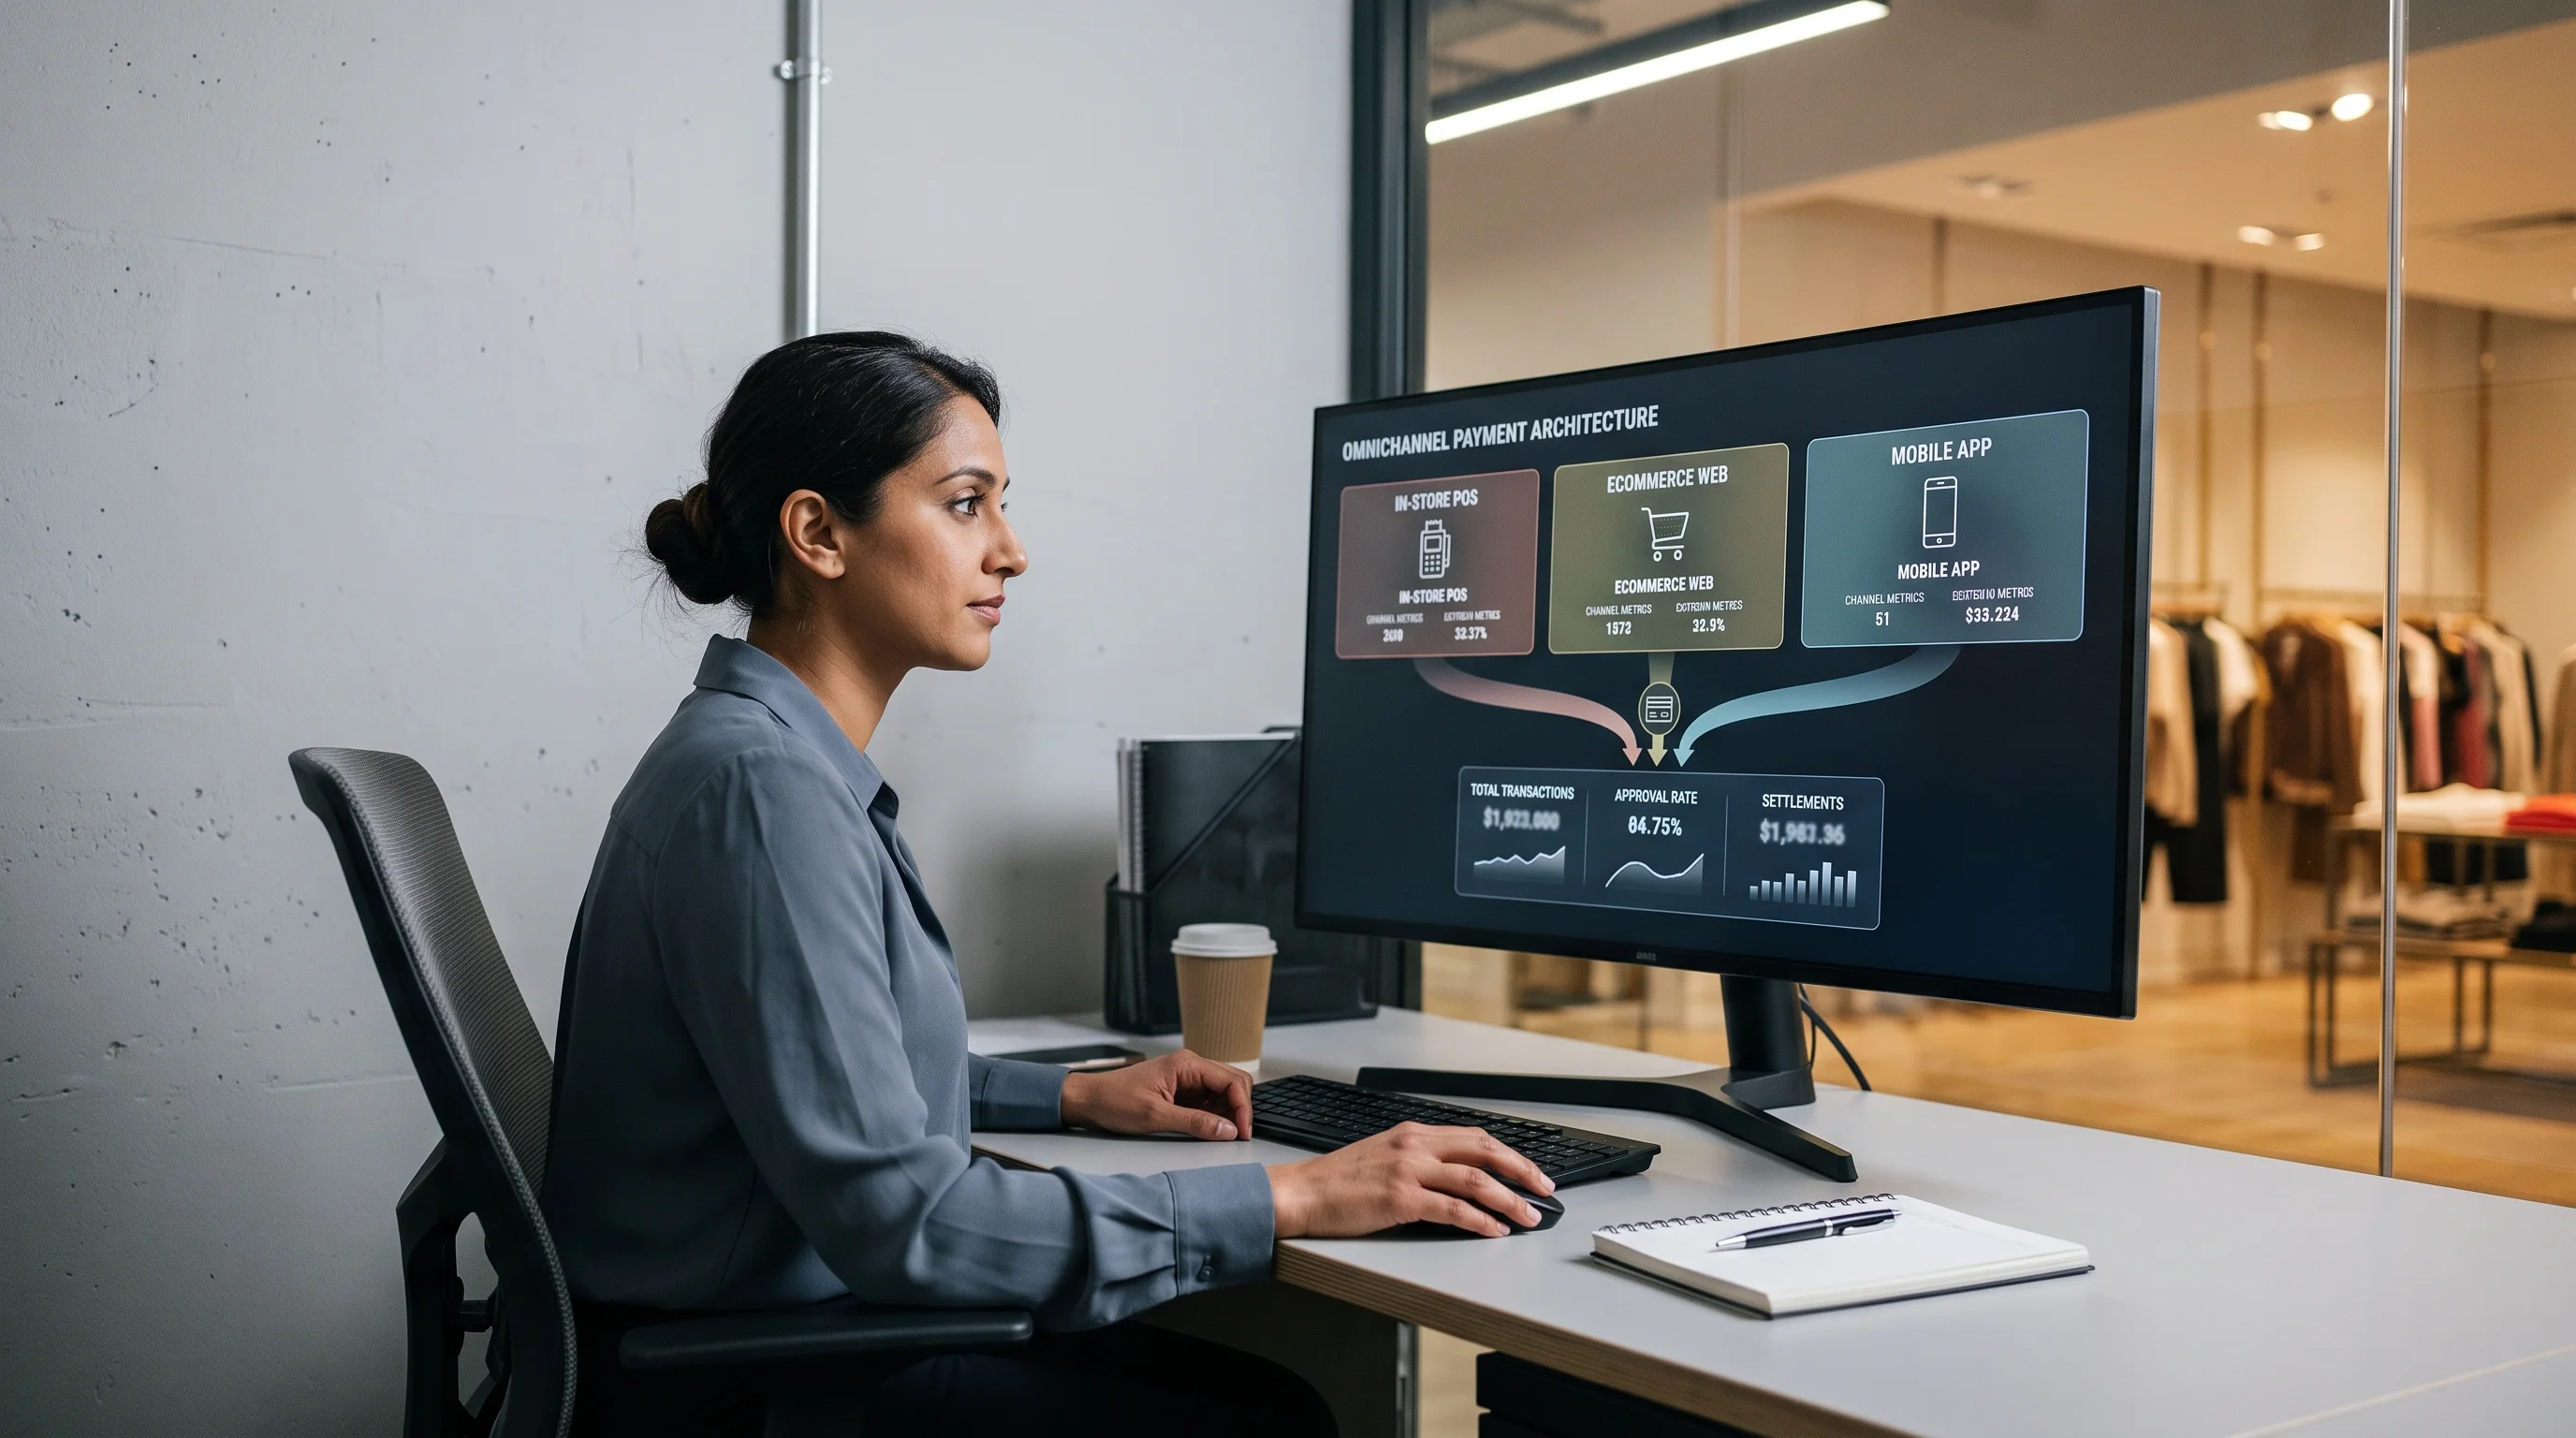
An omnichannel payment solution puts a single platform underneath every channel. In-person transactions, ecommerce payment solutions and in-app payments all route through one integration. The same token vault governs every card-on-file relationship. A card saved during an online checkout is recognised at the point of sale in your store, and vice versa.
That single token layer makes several things possible that multichannel stacks cannot easily replicate: cross-channel returns without manual card re-entry, unified customer payment profiles, consistent fraud scoring built on a complete view of each cardholder rather than a fragmented one, and loyalty mechanics that recognise the customer regardless of where they transact.
The reporting layer changes too. Instead of assembling settlement data from multiple sources every morning, finance teams work from one consolidated view of every channel's activity.
Why UK Enterprises Are Unifying Their Payment Channels
A Single View of the Customer
According to Adyen, 53 per cent of consumers want to buy online and return in-store, yet 42 per cent of businesses have not connected their channels to support that journey.[1] The gap sits directly inside the payment layer. When each channel maintains its own token store, customer identity is local to that channel. A cardholder who bought online is treated as a stranger at the point of sale.
Unifying the token vault changes that relationship. Every transaction, regardless of channel, writes to the same customer profile. Cross-channel returns become a matter of matching the token rather than reprocessing the card. Loyalty programmes attribute purchases accurately. Fraud scoring draws on the full transaction history across all channels, not just the activity visible within one.
Unified Reconciliation and Reporting
Finance teams running fragmented payment stacks spend significant time each period normalising settlement data from multiple processors into a single format before reconciliation can begin. Each provider uses different file structures, different settlement timings and different reference formats. A unified payments platform eliminates that normalisation layer. Every channel produces the same settlement format, the same reference structure and the same reporting view. Month-end close is faster, audit trails are cleaner and the finance team can focus on analysis rather than manual data assembly.
Consistent Fraud and Compliance
Fragmented stacks create fraud exposure that unified platforms do not. When each channel applies its own fraud scoring model with access only to its own data, a fraudster who tests a card in-store and exploits it online moves between systems that cannot communicate. A single platform applies the same rule set, the same velocity checks and the same compliance framework across every channel. The gaps between channel-specific models disappear.
What to Look For in an Omnichannel Payment Platform
Not every platform that markets itself as omnichannel genuinely delivers a single architecture. When assessing enterprise payment gateway solutions, look for the following:
- Channel coverage: The platform should handle in-person POS, online and in-app transactions through one integration, not through separate modules that share branding but not infrastructure.
- Unified tokenisation: A single token vault that creates and manages card tokens consistently across channels. If a card saved online cannot be recognised in-store, the platform is multichannel in practice, whatever the marketing says.
- Single reporting and settlement: One consolidated reporting view covering every channel. Settlement should arrive in a unified format, not as separate files from separate processing endpoints.
- Consistent fraud and compliance: A single fraud scoring engine drawing on cross-channel transaction history, not channel-specific models working in isolation.
- Enterprise-grade integration: API architecture flexible enough to fit an existing enterprise technology stack without requiring a rebuild of each channel's front-end.
ONERWAY's unified payments platform is built for exactly this requirement. UK enterprises can bring their in-store, ecommerce and in-app payment acceptance together through a single enterprise integration, with unified tokenisation, consolidated reporting and a consistent risk engine across every channel. Review pricing built for enterprise scale and speak to the ONERWAY UK team to assess how the architecture fits your current stack.
Conclusion
Running separate payment systems per channel creates cost and risk that compounds as your channel mix grows. Reconciliation takes longer, fraud controls are incomplete and customer experience suffers at every junction where the systems do not connect. A properly unified omnichannel payment solution removes those junctions. One integration handles every channel. One token vault recognises the customer across every touchpoint. One reporting view closes the reconciliation gap. ONERWAY brings that architecture to UK enterprises through a single platform covering payment acceptance across in-store, online and in-app channels. Map your unified payment architecture with the ONERWAY UK team today.
Frequently Asked Questions
What is an omnichannel payment solution?
An omnichannel payment solution is a single payment platform that handles transactions across all your sales channels - in-store, online and in-app - through one integration, one token vault and one reporting view. Unlike multichannel stacks, it connects channel activity into a single customer and financial record.
What is the difference between multichannel and omnichannel payments?
Multichannel payments use a separate processing system for each channel. Omnichannel payments route every channel through one unified platform. The difference is not in the number of channels supported but in whether those channels share the same infrastructure, token store and reporting layer.
Why do enterprises need unified payment channels?
Separate systems per channel create reconciliation overhead, fragmented fraud controls and disconnected customer profiles. A unified payment architecture reduces operational cost, improves fraud coverage and enables cross-channel experiences such as buy online, return in-store.
How does omnichannel payment help fraud prevention?
A unified fraud engine draws on cross-channel transaction history to score each payment, giving it a complete view of cardholder behaviour. Fragmented systems score payments using only channel-specific data, creating gaps that a single platform does not have.
Can a saved online card be used in store?
Yes, on a properly unified platform. A shared token vault means the token created during an online checkout is recognised at the point of sale. The card does not need to be re-entered or re-authorised by the customer.
Resources
[1] Adyen — Benefits of Choosing a Unified Payments Platform